




Asia-Europe rates fall as Suez returns
Asian congestion is pushing carriers toward Suez, increasing Asia-Europe capacity as freight rates soften from mid-year highs
Asia-Europe container freight rates are falling as severe congestion at Asian ports prompts carriers to return capacity to the Suez Canal, according to Sogese’s September Europe Container Market Update.
Drewry’s 3 September World Container Index showed the Shanghai-Genoa rate at US$4,368 per 40ft container, down 10% week on week, while Shanghai-Rotterdam fell 5% to US$4,092. Blank sailings on the trade are also expected to fall from four to one next week.
“The container market is becoming increasingly fragmented by trade corridor, with freight rates, cargo demand and available capacity moving in different directions,” said Andrea Monti, chief executive of Sogese. “Asia-Europe rates have started to soften from their mid-year highs while transpacific markets remain firmer.”
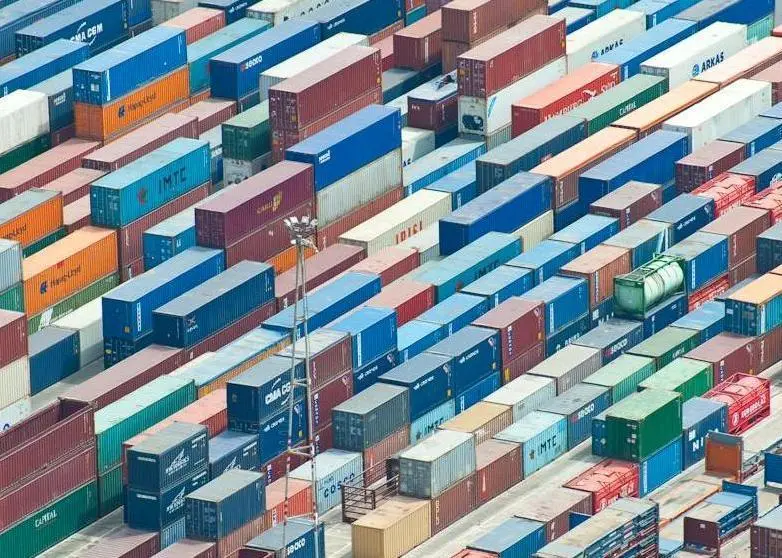
Asian port congestion has reached 4.3 million teu, exceeding the 4 million teu stranded during the pandemic peak, according to Linerlytica data. Meanwhile, diversions around the Cape of Good Hope continue to absorb an estimated 5% to 7% of global container capacity.
MSC, Maersk and Hapag-Lloyd have announced partial returns to Suez, while COSCO and OOCL have expanded Red Sea services connecting Asian ports with Jeddah via the Suez Canal.
“The selective return of services through the Suez Canal adds another variable,” Monti said. “Shorter voyages can increase effective capacity on Asia-Europe routes even without new ships entering the market.”
Sogese said carriers are increasingly adjusting individual services, port rotations and vessel deployments rather than making broad network-wide capacity changes.
For European shippers, this could mean greater capacity availability but less predictable schedules, as services alter frequencies, port calls and transshipment arrangements.
“Congestion has become the more urgent variable,” Monti said. “What has changed is that the cost of waiting has gone up faster than the risk of moving.”
Sogese expects freight rates to soften progressively while remaining above pre-crisis levels. It forecasts selective Suez expansion, gradual Asia-Europe capacity growth, improving equipment availability in parts of Europe and continued tactical carrier adjustments.
The report expects the market to move towards greater balance, with improving capacity availability rather than a rapid return to pre-crisis freight economics.
Related Articles
 PORT & TERMINAL NEWS
 PORT & TERMINAL NEWS
 DIGITAL