




Bulk shipping outlook
The dry bulks, liquid bulks and gas shipping sectors navigated ‘unprecedented global circumstances’ in 2023 and 2024 promises a landscape of ‘continued change and evolution.’ Felicity Landon reports
War, inflation, trade upheavals, environmental pressures – the shipping industry must deal with it all. At a Drewry webinar focusing on bulk shipping, Drewry’s experts set out their views on the year ahead. They painted a challenging and uncertain picture.
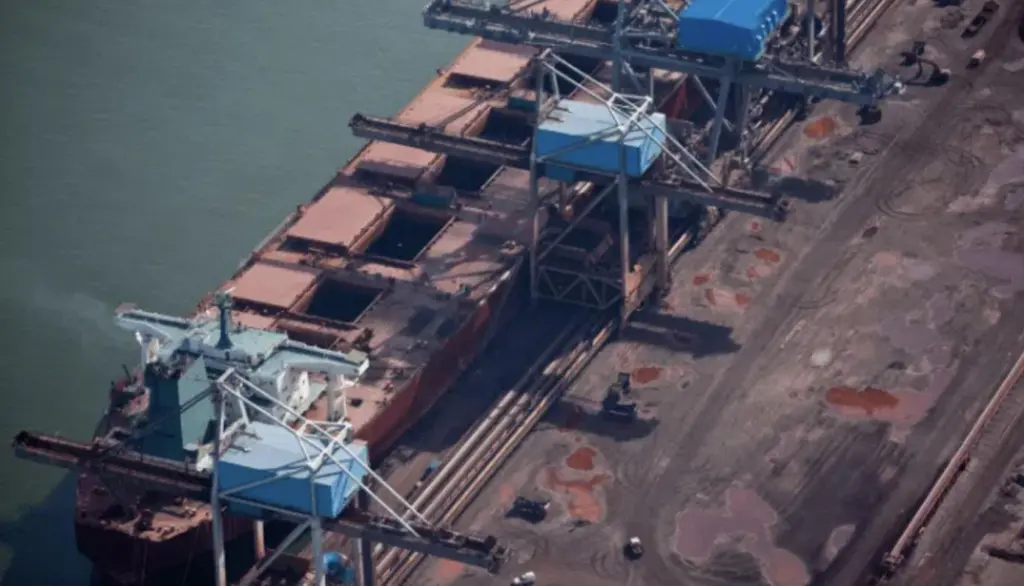
Last year was a turbulent 12 months for the dry bulks sector, especially with the Ukraine war continuing and the new war in Gaza, said Rahul Sharan, Head of Dry Bulk Research, Drewry. The shortage of water in the Panama Canal added to the challenges, along with inflation and other geopolitical tensions.
In 2024, key factors driving the market will be China’s demand for coal and iron ore, and shipping supply side issues based on how ship owners will cope with the EU Emissions Trading System and IMO emissions requirements, said Sharan. “China will keep driving the coal shipping demand in 2024 as it did in 2023. In the past few weeks (late 2023), there have been a couple of mining incidents in China so that a couple of mines might be operating at a below par level, or not operating at all. That means domestic coal production might not be as high in 2024, so imports into China might go further up.”
Aside from China, most steel producing countries imported less iron ore. “However, we believe that with easing pressures on economies, in 2024 there could be positive iron ore trade in all the major economies and the trade will grow more than we have seen in 2023.”
SUPPLY SIDE
On the supply side, the dry bulk shipping orderbook has been very low and remains so for 2024, he said. “Fleet growth will be very restricted, to 1.2-1.3 per cent in 2024. At the same time, because of environmental regulations we might see demolitions going up. The pressure of these regulations could see some older ships heading for the scrapyards.”
The expectation of higher rates might prompt more orders in 2024, he noted – this would have no impact this year but could affect overall earnings in the years to come.
Sharan was asked: “Are handysize vessels slowing leaving the market and being replaced by supramaxes and ports getting bigger? He replied: “Handysize vessels have been very important for specific segments and are not going to go away. Also, many smaller ports are not in the position to handle ships that are bigger than handysize.”
Another key question in dry bulks is what happens in the grain markets this year in the context of the Russia-Ukraine conflict. “We might see more grain coming out of the Black Sea in 2024,” he said.
As for the Red Sea, the diversions away from the Suez Canal come on top of the fact that a lot of cargo was being diverted away from the drought-hit Panama Canal to use the Suez Canal. This, said Sharan, added to overall tonnage demand for the longer voyages. Now, with many ships avoiding the Red Sea and therefore Suez, even more diversions will be required.
WET BULKS DEMAND
Last year was very strong for liquid bulk ship owners as rates surged, said Rajesh Verma. “There were three main reasons behind this. First, surging global oil demand, primarily driven by the return of demand post-Covid. Second, shifting trade patterns because of the Ukraine-Russia war, which mainly benefited mid-size tankers. The increase in China’s refinery capacity added to this. Third, there was a decline in deliveries (of new ships). There was no significant scrapping in the year due to the strong demand and high earnings for crude tankers.”
This year (2024) will see significant change in both demand and supply sides, said Verma. A tight supply of ships will keep rates buoyant despite a deceleration in demand, he predicted. The orderbook has ‘declined sharply’ to a level equivalent to four per cent of the current fleet.
“The fleet growth will shrink. Any increase in scrapping activities is unlikely, but the IMO regulations might have some impact – especially, for example, a slowdown in vessel speed. We believe that tanker owners will continue to enjoy higher rates.”
Although the market looks positive, there are major risks, he said, in the form of geopolitical tensions and any increase in the ‘grey trade’ of Iranian and Russian crude oil.
The product tanker market has been similar to the crude tanker market, with ‘astronomically high’ rates in 2023, said Verma. “In addition to the surge in demand, the shift in trade patterns has played a significant role in the product tanker market with a surge in tonne mile demand.”
An expected slowdown in crude oil demand will affect the product tanker market too, he added, while refinery capacity additions in key oil consuming countries such as Nigeria will also reduce shipping demand.
One unknown is what happens with oil-rich Venezuela. “If sanctions were removed, any recovery would be gradual but would have a positive impact on the demand for tankers to Asia. Any long-haul trade would increase. Similarly, any delay in the Dangote refinery in Nigeria would be positive for the crude oil tanker market.”
The LNG market will be volatile this year, with fleet growth surpassing trade growth, and hence putting pressure on charter rates, said Aman Sud.
He expects European storage levels to be at about 40 percent towards the end of the heating season, and therefore less hurry/urgency to refill. “Having said that, the region will be aware of what happened in 2022 with the energy crisis, so is putting a lot of importance on storage.”
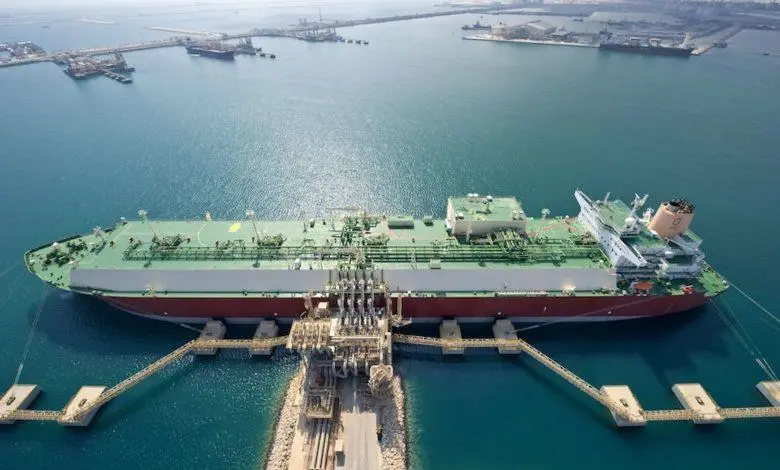
The LNG fleet picture is entirely different to the dry and liquid bulk tankers scene. The fleet is expected to expand by nine per cent this year: “Expect charter rates to be a little bit subdued in the second, third and fourth quarters. After 2024, the phasing out of vessels due to the new environmental (EEXI) regulations and larger liquefaction plants coming on-line from 2025 will re-establish the equilibrium, and the market will then be very tight until at least 2028. We believe this is going to be a sector to watch out for over the next five years.”
The LPG market saw a surge in US-Asia trade in 2023 adding to tonne mile demand and the Panama Canal restrictions also affected LPG shipping rates, said Sud. “Restrictions due to draught limits in the Panama Canal are expected to persist through 2024.”
LPG growth is expected to slow to two per cent this year. Ammonia, however, is expected to increase by seven per cent as decarbonisation picks up speed. “A lot of companies are planning to increase their ammonia trade.”
The LPG fleet is expected to expand by four per cent in 2024, with 41 vessel deliveries – the majority being VLGCs.
Apart from the geopolitical tensions, Panama Canal limits and new deliveries, factors that could cause volatility in the LNG/LPG sector this year include fossil fuel reduction, internal threats and political risk – particularly in this ‘year of elections’ “Any changes in countries’ energy policies [post election] and how they view decarbonisation is going to affect the sector.”
Related Articles
 OPERATIONS
 OPERATIONS
 OPERATIONS