Asian ports are rethinking resilience — and the smart money is following
Record volumes, rerouted trade and a harsher climate are forcing Asia’s ports to stop treating resilience as a civil-engineering problem. Dr David Rissik, APAC Lead for Risk and Resilience at BMT, argues that the ports pulling ahead are the ones designing for flexibility across energy, data and operations — and that this is now a commercial question as much as an engineering one.
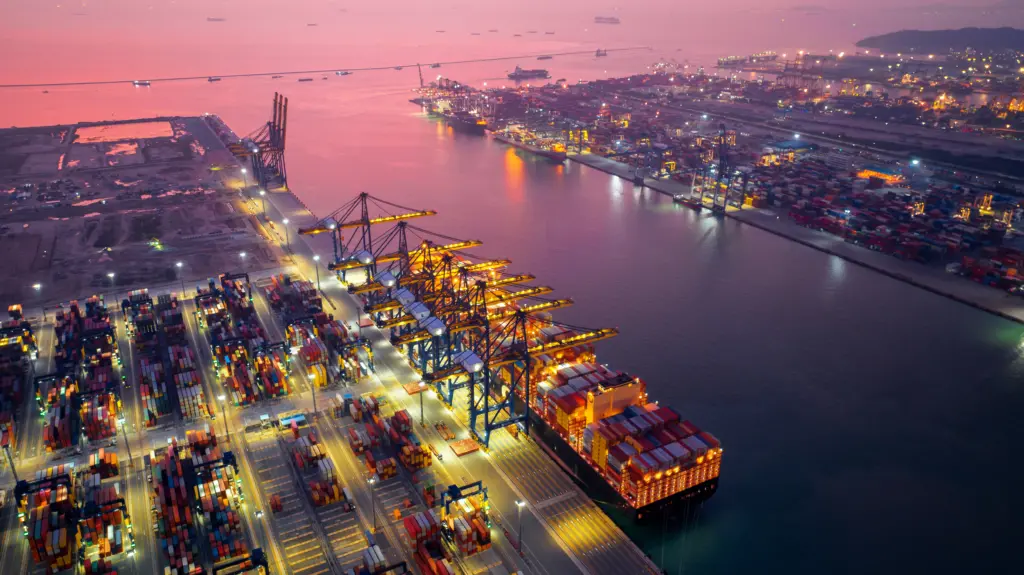
In February this year Port Hedland, the largest bulk export port in the world, cleared its harbour on a Friday and had ships back alongside by Sunday lunchtime. Cyclone Mitchell had passed through in between. Nothing broke. The port simply did what it had rehearsed, and the iron ore kept moving. Six months later, Shanghai and Ningbo closed for four days in a typhoon season so severe that one analyst called it “special”, and the queue of ships waiting for a berth worldwide climbed past anything we saw during the pandemic. In the same year, the Strait of Hormuz disruption sent services back around the Cape and redrew the schedules of every hub between Jebel Ali and Busan.
What strikes me about 2026 is not that ports closed; ports have always closed. It is which ones reopened fastest, and why. The answer, increasingly, has very little to do with the thickness of their quay walls.
For most of my career, resilience in port planning meant building harder: higher deck levels, heavier revetments, deeper channels, bigger breakwaters. That still matters. But the ports I now see pulling ahead across Asia are the ones that have reframed resilience as a question of options rather than strength. They are asking not “how do we withstand this?” but “how many different ways do we have of staying open?”
“Resilience used to mean building harder. In Asia today it increasingly means building optional.”
The commercial pressure behind that shift is easy to see. Drewry’s analysis of nine major ports shows terminal capacity grew by about 21 per cent between 2019 and 2026 while volumes grew 28 per cent, and Greater China utilisation is forecast to pass 95 per cent by 2030. A terminal running at 90 per cent berth utilisation takes roughly a week to recover from a single day’s disruption; at 75 per cent, about two days. Yet operators, as Drewry also observes, are unlikely to finance large amounts of spare buffer capacity that earns nothing in a normal year. So the slack has to come from somewhere other than concrete.
The Asian Development Bank puts the stakes bluntly: half the world’s port capacity and two-thirds of its container traffic sit in this region, meaning physical damage to transport infrastructure could cost between $12 billion and $54 billion a year, and the trade losses from a single port failure can be a hundred times the cost of the damage itself. That hundred-to-one ratio is the number I would ask every port board in the region to sit with. It says the asset you are protecting is not the wharf, but the ability to operate.
In our own climate risk work with ports across Australia and South-East Asia, the things that actually stop a terminal are rarely structural. They are high winds locking down gantry cranes. Heat that cuts the productivity of a yard workforce by the afternoon. Storm tides reaching the switchgear that feeds the reefer stacks. Smoke or fog closing the channel to pilotage. Flash flooding in the gate area. Maintenance dredging that slips a season because the weather window was lost. Each is an operational failure before it is an engineering one, and each has a different, often cheaper, fix than raising the deck. Writing those impacts down, port by port, turns a vague anxiety about climate into a list an operations manager can act on.
“The ports I worry about are the ones with no plan for the day the cranes are locked down by wind, the yard is under water and the gate system is offline — all at once.”
That compounding is the second thing 2026 has taught us. The trade press reports typhoons, chokepoint closures, tariff rerouting and cyber incidents as separate stories. A port experiences them as one system. The ports that absorbed the Hormuz shock best, Singapore among them, were the ones whose operations, data and energy supply could flex under stress. Port Klang and Colombo took the overflow and congested; that is not a criticism, it is a reminder that resilience is a property of the network as much as the node, and of the grid, the workforce and the hinterland a port depends on.
Which raises the question the buffer-capacity debate leaves open: not whether to carry slack, but how much, in what form and where in the chain. It is answerable. In Western Australia we modelled a proposed five million tonne a year magnetite export chain for an Australian–Japanese joint venture as a single system: from the mine, down a 110-kilometre slurry pipeline, through dewatering and a port stockpile, onto a transhipment vessel and out to Capesize ships at anchor in King George Sound. Rather than assume the weather, the simulation ran ten years of recorded wind, wave and current conditions at hourly resolution and let them decide when the transhipper could safely come alongside and when it could not. The answer was not a bigger port, but a precise understanding of how large the stockpile had to be to ride out a run of inoperable days, which vessel configuration earned its cost, and where in the chain a delay would actually show up in the annual export figure. The slack was sized, costed and placed where it did most good. A container terminal facing a typhoon season can be treated the same way: concrete traded for information, if the modelling is done properly. We have applied the same systems-based thinking to port development at Samalaju in East Malaysia, and the approach is equally relevant to the transhipment hubs around the Malacca Strait, whose dependence on relayed cargo creates its own operational exposure.
Energy is where the rethink is becoming most visible, and most commercial. The Singapore–Los Angeles–Long Beach green and digital corridor was renewed this year, and tellingly it now covers cybersecurity, interoperability and port-to-port data connectivity alongside fuels. Hong Kong is seeing the region’s first dedicated zero-emission shore power venture, aiming at more than 30 terminals by 2030. Across the region I see ports becoming energy systems in their own right: rooftop solar, electrified yard equipment, biofuel blending, hydrogen trials for heavy yard vehicles, and the early bunkering infrastructure for methanol and ammonia. The decarbonisation case is well rehearsed; the resilience case is just as strong and less often made. A terminal that can draw on more than one power source, and that holds energy as well as cargo, has an option a diesel-dependent competitor does not.
Digital systems cut both ways. Yangshan’s fully automated Phase IV now runs on a digital twin with cranes controlled from 100 kilometres away; Tuas has passed 25 million TEU on its way to being the largest automated terminal in the world; Japan is funding remote-operated cranes at its strategic container ports. Predictive analytics, port community systems and digital twins give operators something they never had before: the ability to simulate a disruption on Tuesday and re-sequence the yard before it arrives on Thursday.
Decision support does not have to be grand. At the Port of Bundaberg in Queensland we updated a three-dimensional hydrodynamic model of the Burnett River entrance, validated it against current measurements taken from a boat across a full spring tide, and turned it into two practical things: input files so that marine pilots could practise the approach in a ship simulator, including river flood scenarios from 100 to 5,000 cubic metres a second and the channel as it will look after planned dredging, and a half-hourly tidal atlas for the pilots’ own reference. None of that is a mega-project, but it means the people who have to bring a ship in the morning after a flood have already done so, several times, in conditions the channel has not yet seen. We have just opened a digital innovation and simulation centre in the UK to do this kind of work at scale, for commercial ports, pilots and maritime authorities as much as for navies: full-mission bridge trials, remote-operations concepts, incident reconstruction, with the same models running from a laptop to a full bridge so that a port in Queensland or Johor can take part without leaving home. Rehearsal, in my view, is one of the cheapest resilience investments a port can make.
The flip side is that maritime cyber incidents doubled in 2025, and the more automated a terminal, the more a single software failure looks like a cyclone. Digital resilience and cyber resilience are now the same conversation, and I would suggest they are not yet being had in the same room.
“Resilience comes from options. A terminal that can switch power, reconfigure yard operations and reroute critical data can adapt to disruption rather than simply wait for it to pass.”
The fourth dimension, operational flexibility, is the one the industry talks about least, perhaps because it does not come with a procurement line. It is the choice to design berths that can take more than one commodity, to keep a second landside mode genuinely available rather than nominally so, and to set an explicit recovery-time target for each critical function and plan backwards from it. In master planning terms it means scenario-based plans rather than single forecasts, with capital going to the measures that buy the most operating time per dollar, which are often not the largest.
None of this is evenly distributed. UNESCAP’s review this year found several economies in the region, including some with very large ports, still have no standalone port design standard, and the IAPH and ADB’s latest tracker warns the gap between Asia’s leading and lagging ports is widening. The hubs will manage. The second-tier gateways and the island ports, where a closure is a national event, are the ones that most need this reframing and have the least room to fund it.
Which brings me to the commercial point. Disclosure regimes such as IFRS S2 have moved climate risk into the boardroom, as I argued in these pages last year; the next step is moving it from the boardroom into the operations room, because investors, insurers and lenders are starting to price resilience. The ADB’s estimate that protecting just 53 of the region’s largest ports could cost $50 billion is an invitation as much as a warning, because that capital is looking for ports that can demonstrate a modelled recovery time rather than an asserted one. Resilience is becoming a condition of finance, a lever in concession negotiations and a factor in where carriers place their networks when they redesign them, as they have been doing all year. It is also reshaping who pays. Across Asia the elements that make a port resilient at its foundations, the channels, breakwaters and protective works, are increasingly carried by the public purse while operators invest in the terminal above: Vietnam is funding the Cai Mep–Thi Vai channel and the breakwaters at Lien Chieu in Da Nang, Cambodia has drawn on Japanese finance for Sihanoukville, and Taiwan’s government funded the infrastructure beneath Kaohsiung’s first fully automated terminal. That division of labour, which this magazine examined in 2023, looks less like a financing convenience and more like a resilience model.
“Investors are starting to price resilience. A port that can show how it stays open is a port that gets financed.”
Asian ports are rethinking resilience because the region’s trade has given them no choice. The ones that come through the next decade strongest will, I suspect, be those that stop treating it as the engineering department’s problem and start treating it as the operating model. Port Hedland’s Sunday lunchtime was not luck. Harder is still good. Optional is better.
Dr David Rissik is Programme Manager – Coastal and Maritime and APAC Lead for Risk and Resilience at BMT, the international maritime engineering and design consultancy. He advises port authorities, terminal operators and governments across Australia and the Asia-Pacific on climate risk, adaptation planning and resilient infrastructure.

Related Articles
 EXPANSION & DEVELOPMENT
 CONCESSIONS & INVESTMENTS
 CONTAINER & CARGO HANDLING